If you have multiple debts and any extra cash left after minimum payments, the debt snowball vs avalanche question comes down to more than math. Both strategies tell you to make the minimum payment on every account and then send additional money to one target. Debt snowball prioritizes the smallest balance; debt avalanche prioritizes the highest interest rate. The right choice depends on whether you get more value from saving interest or from seeing a balance hit zero.
How the Debt Snowball Works
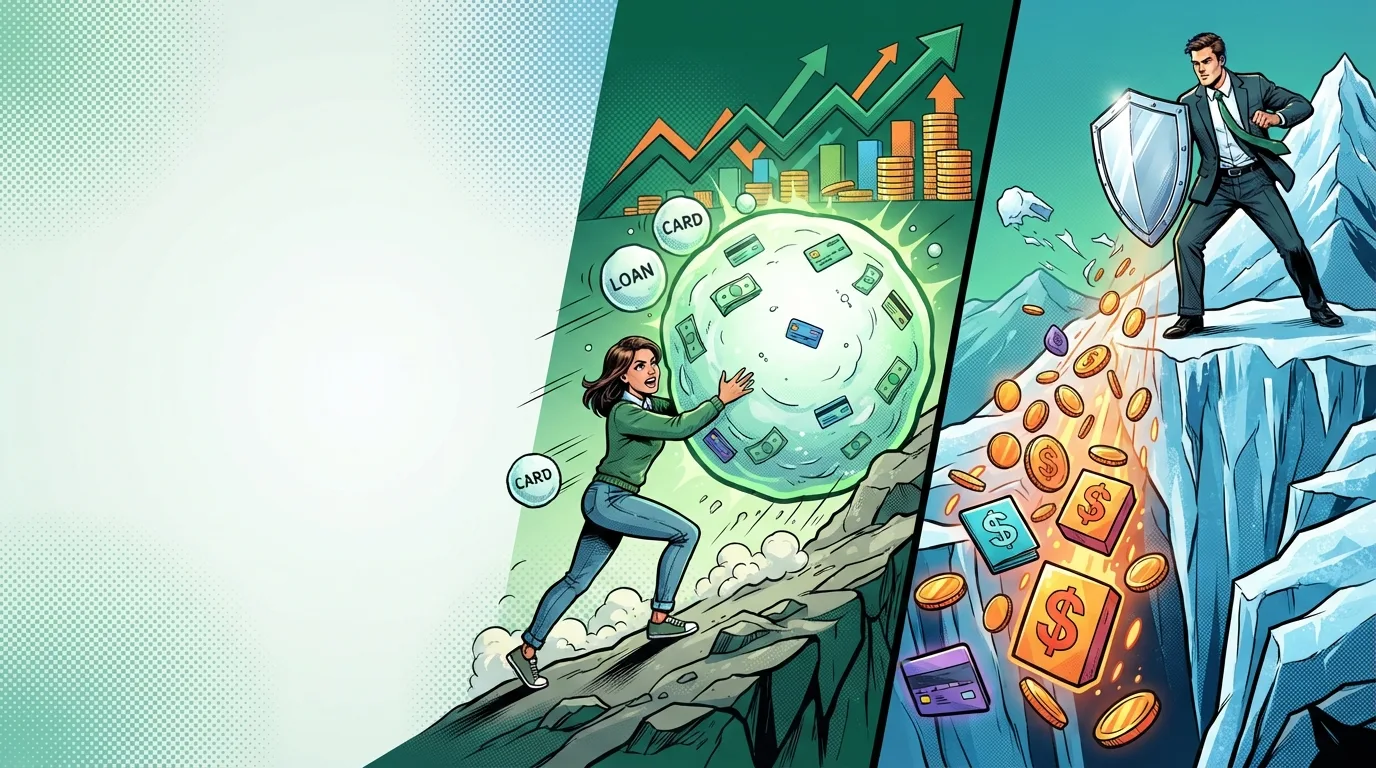
The debt snowball method ignores annual percentage rates (APRs) when you decide which balance to attack. List every debt by what you owe, from smallest to largest.
- Write down the balance of each debt.
- Arrange the debts from the lowest balance to the highest balance.
- Continue making the minimum payment on all accounts.
- Send every extra dollar to the smallest balance.
- When that balance is paid off, roll that full payment amount to the next-smallest debt.
For example, suppose you have an $800 credit card with an 8% APR and a $5,000 credit card with a 21% APR. The snowball method targets the $800 balance first because it is small, even though the larger card charges more than twice the interest. That first payoff can arrive in a few months, producing a quick, visible win. The trade-off is that the 21% balance keeps growing while you focus on the cheaper account.
How the Debt Avalanche Works
The debt avalanche method, sometimes called debt stacking, arranges debts by APR, from highest to lowest.
- Write down the balance and annual percentage rate for each debt.
- Sort the list from highest APR to lowest APR.
- Make at least the minimum payment on every account.
- Put all extra money toward the highest-APR debt.
- After that debt is gone, apply the same total payment to the next-highest APR debt.
Using the same example, avalanche targets the $5,000 balance at 21% APR before the $800 balance at 8% APR. You may not see an account paid off as quickly, but your extra payment is reducing the most expensive interest first. If you keep the same monthly payment and do not add new debt, avalanche will almost always cost less in total interest than snowball.
Debt Snowball vs. Avalanche: Key Trade-Offs
The table below compares the practical trade-offs.
| Factor | Debt snowball | Debt avalanche | |---|---|---| | Target order | Smallest balance first | Highest APR first | | First payoff | Quick in most cases | May take longer | | Total interest | Usually higher | Lowest in most situations | | Good for | Building momentum | Saving the most money |
These differences matter most when your smallest balance has a much lower APR than a larger balance. If the smallest balance also carries the highest APR, the two methods point to the same first debt. Neither method creates cash; each one only changes the order you use the cash you already have.
Choosing a method is not permanent. You can switch if your budget changes, but make sure the new plan still covers every minimum payment. The Federal Trade Commission’s debt-repayment guidance lists both strategies as common tools, and it stresses that the plan you can stick with is the one that gets you out of debt.
How to Choose Between the Two Strategies
Begin by reviewing your cash flow, monthly expenses, and spending triggers. Avalanche is likely the better choice if your main goal is minimizing interest and you are comfortable watching a large, expensive balance shrink slowly. Snowball may work better if you have abandoned payoff plans in the past or if motivation is a weakness.
Before you commit extra money to either plan, set aside a starter emergency fund of $500 to $1,000. Without this cushion, one medical bill or car repair can push you back onto credit cards and erase your progress.
You can also combine the strategies. Start with the avalanche order, but look for any debt that is within one or two months of being paid off. If you find one, clear it first for an early win, then go back to the highest-APR debt. This hybrid approach gives you momentum while keeping most of your interest savings.
Bottom Line
In a debt snowball vs avalanche comparison, the best plan is the one you will follow for as long as it takes. Avalanche saves more interest and usually finishes earlier if you make the same extra payment from month to month. Snowball makes the payoff process easier for many people because small debts disappear quickly. Pick one, automate your payments, and review your progress every few months.