Choosing health insurance plan options can feel overwhelming, especially with the wide variety of metal tiers, provider networks, and cost-sharing structures available. But having a clear understanding of how different plans work—and what you actually need in terms of medical care, budget, and provider flexibility—can make the decision much easier. This guide walks you through the most common plan types and the key factors to compare so you can make an informed choice during open enrollment or a qualifying life event.
The Four Core Plan Types: HMO, PPO, EPO, and POS
Most health insurance plans fall into one of four categories. Each balances access to providers, referrals, and out-of-pocket costs differently.
- Health Maintenance Organization (HMO): These plans require you to choose a primary care physician (PCP) who coordinates all your care. You typically must obtain a referral to see a specialist. HMOs have the most restrictive networks—only covering care within the plan’s network, except for true emergencies—but they usually come with the lowest premiums and deductibles.
- Preferred Provider Organization (PPO): PPOs offer more flexibility. You can see specialists without a referral and can go out-of-network, though you’ll pay more than if you stay in-network. For that freedom, you’ll generally pay higher monthly premiums and sometimes face separate deductibles for in-network and out-of-network care.
- Exclusive Provider Organization (EPO): This is a hybrid of an HMO and a PPO. EPOs do not require referrals, but they do not cover any out-of-network care, except emergencies. These plans often have lower premiums than PPOs and are a good middle-ground if you rarely need to see a specialist.
- Point of Service (POS): A POS plan is a mix of HMO and PPO features. Like an HMO, you have a PCP who provides referrals. However, you are also allowed to see out-of-network providers with higher costs, similar to a PPO. POS plans are less common today but still offered through some employers.
Which is best? If you want the lowest premium and are comfortable with a narrower network, HMOs/EPOs are attractive. If you have ongoing specialist needs or desire freedom to see out-of-network providers, a PPO or POS may be worth the higher cost.
Comparing Costs Beyond the Monthly Premium
Do not choose a plan simply because it has the lowest monthly premium. You must also evaluate the following cost elements, especially if you expect regular medical visits, prescriptions, or a major procedure:
- Deductible: The amount you must pay out-of-pocket before your insurance begins to share costs. Plans with low premiums often have high deductibles (e.g., $8,000 or more).
- Copayment (copay): A fixed fee you pay for doctor visits, specialists, or prescriptions. Plans vary—some charge a $10 primary care copay, others require you to meet your deductible first.
- Coinsurance: After you meet your deductible, you pay a percentage (e.g., 20%) of covered services; the insurer covers the rest. Lower coinsurance percentages mean lower out-of-pocket costs but often higher premiums.
- Out-of-pocket maximum: The most you’ll pay during the year for covered in-network care. Once you hit it, the insurer pays 100% for covered services. This limit protects you in case of a serious medical event.
- Prescription drug formularies: Check whether your regular medications are covered and what tier they fall into. High-tier drugs can cost hundreds more than generic or preferred alternatives.
- In-network vs. out-of-network costs: If you prefer a specific doctor or hospital, make sure they are in-network. Seeing an out-of-network provider can quickly result in balance billing or zero coverage under an EPO or HMO.
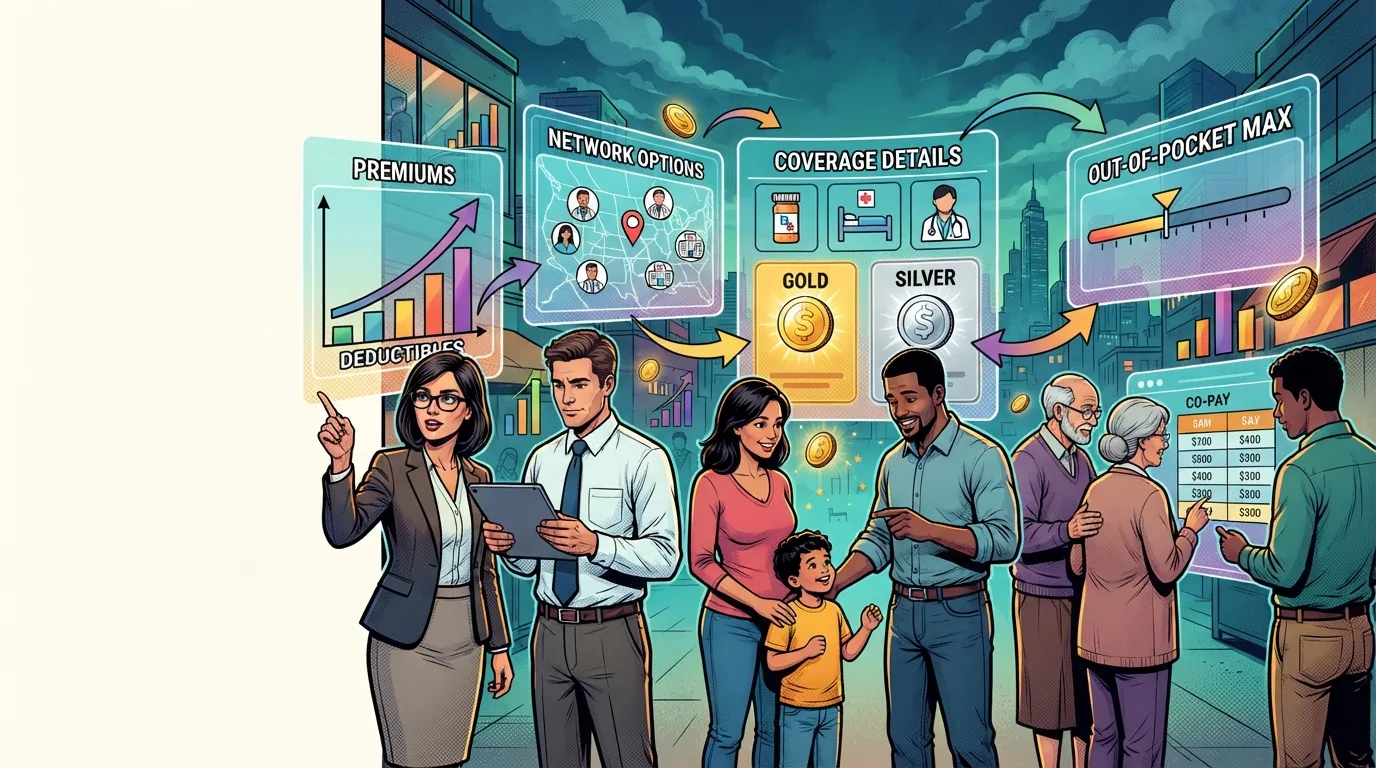
Use a plan comparison chart to list these elements side-by-side. Even a small difference in the out-of-pocket maximum can make a large financial difference during a health emergency.
Marketplace Plan Tiers (Metal Levels) and Catastrophic Plans
If you’re shopping on the Health Insurance Marketplace under the Affordable Care Act (ACA), plan options are grouped into metal tiers based on how you and the insurer split costs:
- Bronze: Similar to a high-deductible health plan (HDHP). Lowest monthly premium, highest deductibles and out-of-pocket costs. Usually covers around 60% of average medical spending.
- Silver: Moderate premium and moderate cost-sharing. The insurer covers about 70% of average costs. If you qualify for premium tax credits, subsidies are based on Silver plan costs.
- Gold: Higher premium but lower deductibles, copays, and coinsurance. The insurer covers about 80% of average costs. Good if you use medical services frequently.
- Platinum: Highest monthly premium, lowest out-of-pocket costs. The insurer covers about 90% of average costs. Rarely the best value unless you have significant and predictable medical expenses.
- Catastrophic plans: Available only to people under 30 or those with certain hardship exemptions. These have very low premiums, very high deductibles, and mainly protect you from worst-case scenarios.
To estimate which metal tier works best, consider your “expected use”: if you’re healthy and rarely need care, a Bronze or Silver plan with a Health Savings Account (HSA) could be cost-effective. If you need regular treatment or constant medication, a Gold plan may save you money despite a higher premium.
Employer-Sponsored vs. Individual Marketplace Plans
Most Americans get coverage from an employer, and that context changes how you compare health insurance plan options.
- Employer-sponsored plans: You may be offered only a handful of choices. Employers typically pay a portion of the premium, and employees cannot apply for premium tax credits on the Marketplace if affordable employer coverage is offered. You may also choose between a PPO and a POS plan, and often have access to flexible spending accounts (FSAs) or health reimbursement arrangements (HRAs).
- Marketplace individual plans: If you are self-employed, unemployed, or uninsured, you can buy a plan through Healthcare.gov or a state-based marketplace. You may qualify for premium tax credits and cost-sharing reductions based on household income. You select a metal tier and plan type (most are HMOs, EPOs, or PPOs) with prices that do not depend on your health history.
- Short-term health insurance: Be careful: what is often called “short-term” or “limited-duration” insurance is not considered full coverage under the ACA and does not meet the individual mandate criteria (in states where it exists). It typically denies coverage for pre-existing conditions and caps benefits, so it is rarely a comparable option, but it is sold outside the Marketplace.
Every plan’s Summary of Benefits and Coverage (SBC) must be presented in a standard format that shows covered services and cost-sharing examples. Review that document for an accurate apples-to-apples comparison.
Practical Tips for Choosing Your Health Insurance Plan
Before you finalize your decision, take these steps:
- List your doctors and pharmacies. Confirm they are in-network for each candidate plan.
- Review prescription coverage. Look up each medication you take in the plan’s formulary; note tiers and any prior-authorization requirements.
- Estimate your total costs. Do not compare premiums alone. Add expected deductibles, copays, coinsurance, and out-of-pocket maximums.
- Check if your preferred providers are accepting new patients. Even if listed as “in-network,” a doctor may have a full panel.
- Understand the referral and prior authorization rules. HMO and POS plans may require referrals; some PPOs now limit gatekeeping but still require pre-approval for certain imaging or surgeries.
- Look into financial assistance. Even if you think you don’t qualify for subsidies, run the numbers. Income changes can make you eligible for tax credits on the Marketplace that significantly reduce your premium.
And do not ignore the role of open enrollment periods. For Marketplaces, open enrollment usually runs from November 1 to January 15 (federal), but dates vary by state. Missing it means you must qualify for a special enrollment period through a life event like marriage, birth, or loss of other coverage. Employers set their own annual enrollment windows, typically in the fall.
Bottom Line
Choosing health insurance plan options is not about finding a plan that covers “everything”—it is about matching your medical needs, financial ability, and provider preferences to the right structure. Start by understanding the four core plan types (HMO, PPO, EPO, POS), then use cost-sharing metrics and the ACA metal tiers to rule out plans that are either too expensive each month or too costly when you actually need care. Always read the Summary of Benefits and Coverage, verify network statuses, and calculate not just the premium but the true expected annual cost. With a methodical approach, you can secure a health plan that gives you peace of mind without breaking your budget.