When you shop for car insurance, you'll find that one-size-fits-all coverage doesn't exist. Auto insurance coverage options vary by state regulations, your vehicle's age, your financial situation, and your personal comfort with risk. Taking the time to understand what each type of coverage does—and which coverage types you can skip—will help you build a policy that protects you where it counts and doesn't drain your budget.
Basic Auto Insurance Coverage Types
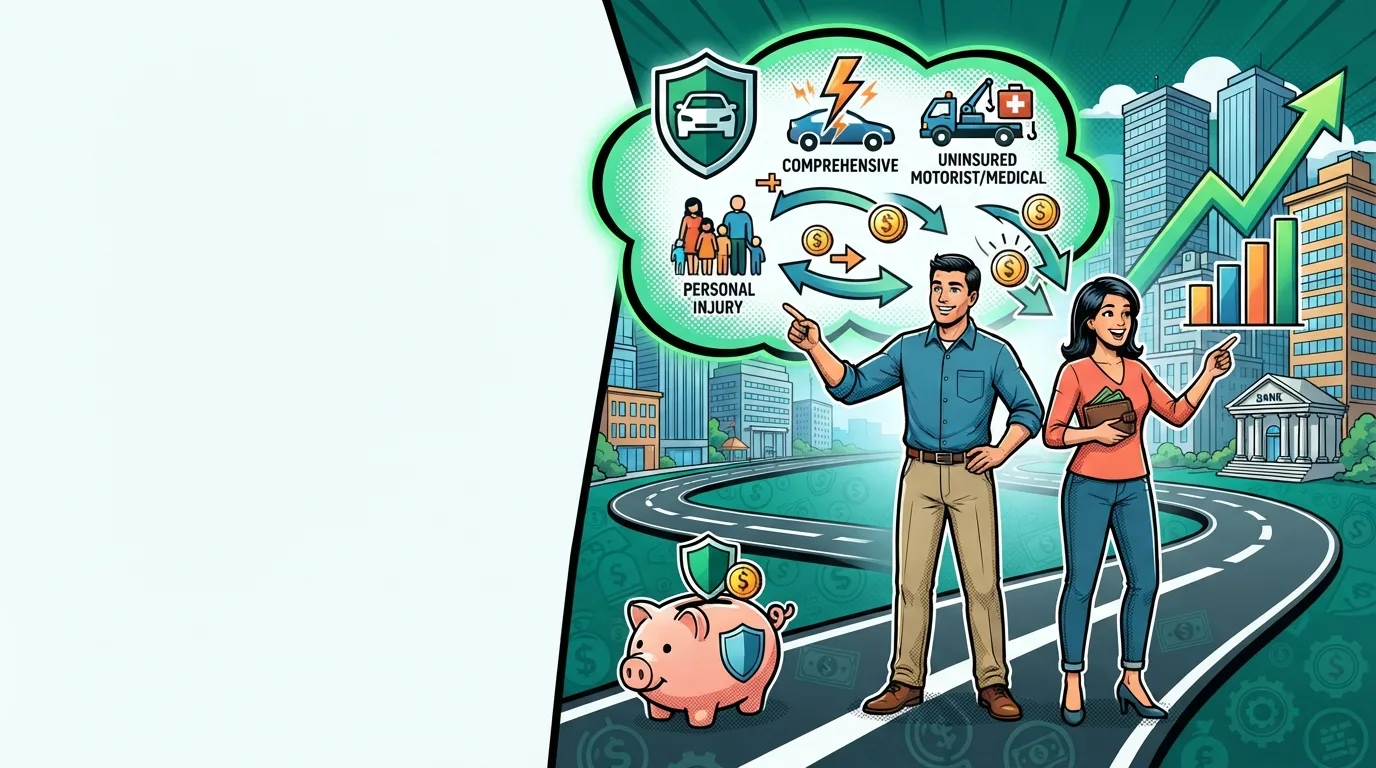
Auto insurance policies are built from several standard coverage components. Most states require a certain amount of liability coverage, and your lender will also mandate physical damage coverage if you lease or finance. Here are the four building blocks you'll see in virtually every policy:
- Bodily injury liability (BI) pays for medical bills, lost wages, and sometimes legal fees for others injured in a crash that you cause. It does not cover your own injuries.
- Property damage liability (PD) pays for repairs to the other driver’s vehicle, as well as damage to property like fences, mailboxes, or guardrails.
- Collision coverage pays to fix your own vehicle after a crash with another car or object. It is optional unless required by your lender.
- Comprehensive coverage covers non-crash damage to your own car—theft, storms, fire, vandalism, hitting a deer, or a cracked windshield. Comprehensive is also optional once you own the car free and clear.
Important nuance: The dollar amounts for liability coverage are typically expressed as three numbers, such as 25/50/25, meaning $25,000 per injured person, up to $50,000 total for all injuries, and $25,000 for property damage. These are the mandated minimums in many states, but minimal limits often don't provide enough real-world protection.
Additional Coverage Options Worth Considering
Besides the core protections, insurers offer a range of optional auto insurance coverage options that close common gaps:
- Uninsured/underinsured motorist coverage (UM/UIM): Pays for your medical bills if an at-fault driver has no insurance or not enough. Some states require it; others allow you to reject it in writing. It's especially valuable given that about one in eight drivers nationwide is uninsured, according to the Insurance Information Institute.
- Medical payments coverage (MedPay) or personal injury protection (PIP): Covers you and your passengers' medical expenses after an accident, regardless of who is at fault. In no-fault states, PIP may be mandatory and can also cover lost income or rehabilitation.
- Gap insurance: In a major crash, your car loses value immediately. If you owe more on your car loan or lease than the vehicle's depreciated value, gap insurance reimburses you for the shortfall between the actual cash value and your loan balance. This is critical for new-car buyers who put little down.
- Rental reimbursement: Covers the cost of a rental car while yours is being repaired after a covered claim. It's a relatively cheap add-on, usually under $2 per month, but not standard.
- Roadside assistance: Most insurers offer emergency towing, battery jump-start, flat-tire and locksmith services as an endorsement or a separate product. It can be worth buying if you don't already have it through your automaker or a credit card.
How to Choose the Right Limits
Your state minimums may be tempting as the cheapest option, but think about what you have to lose. If you cause a serious accident and your liability limit is $25,000 but the injured person's medical bills total $200,000, the other party—or their insurance—can sue you personally and go after your bank accounts, wages, and home.
Industry guidelines generally recommend:
- Bodily injury liability: At least $100,000 per person and $300,000 per accident, if you have sizable assets.
- Property damage liability: Consider $100,000 or more if you can afford it; minimal coverage may not cover a brand-new vehicle or structural damage in an at-fault crash.
- Uninsured motorist: Set equal to your BI limits to avoid a coverage gap.
How much you need also depends on your state's no-fault laws and personal exposure. If you're young and have no assets, the bare minimum might be financially acceptable, but it won't give you much protection against lawsuits. For most people, carrying liability limits above the state minimums is smart.
Deductibles, Premiums, and Out-of-Pocket Costs
Deductibles apply to collision and comprehensive only. This is the amount you pay out-of-pocket before the insurer covers a claim. A higher deductible lowers your annual premium, but it also raises your financial risk if you make a claim. A $1,000 deductible could reduce your monthly premium by 10% to 40% compared with a $500 deductible, depending on the carrier and state.
The best approach:
- Choose the highest deductible you can comfortably pay in cash if your car sustains unexpected damage. For most people that means $500 to $1,000.
- If your vehicle is paid off and worth only a few thousand dollars, you may want to drop comprehensive and collision entirely, since premiums plus deductibles and repairs can exceed the car's value.
When to Drop Coverage on an Older Vehicle
A common rule of thumb: If your collision and comprehensive premiums cost more than about 10% to 20% of your car's actual cash value annually, it may be time to drop those coverages. For example, a $3,000 car with $900 in yearly comprehensive and collision insurance is not cost-effective for most budgets. However, first confirm that you have no lease or loan obligations requiring coverage.
Bottom Line
Auto insurance coverage options exist to let you customize your protection. Start by meeting state requirements, then build outward: liability insurance protects your assets, uninsured motorist coverage guards against hit-and-runs, and physical damage coverages reimburse you for repairs to your own car. Skip add-ons that duplicate coverage you already have from other sources, and adjust your deductibles to find a balance between premium savings and out-of-pocket exposure. Review your policy at least once a year since your car's value and life circumstances change.